2026 Homebuyer's Guide to Savings
5 Smart Ways to Minimize Closing Costs & Maximize Allowable Credits

Most home buyers overpay at closing, simply because they don’t know what’s negotiable and what isn’t.
For more than 20 years, we’ve helped buyers uncover real, legitimate savings hidden inside the closing process. This is the same advice we give our customers, friends, and family to avoid unnecessary fees and maximize allowable credits.
You'll learn how to:
 Spot and avoid unnecessary “junk fees”
Compare title and settlement costs correctly
Identify credits that can legally reduce your cash-to-close
Ask the right questions before you sign
Keep more money in your pocket at closing
No sales tricks. No fine print games. Just transparent guidance from professionals who’ve been doing this for decades.
💡The smartest way to buy a house can be found in these 5 tips.
FAQs: Closing Costs

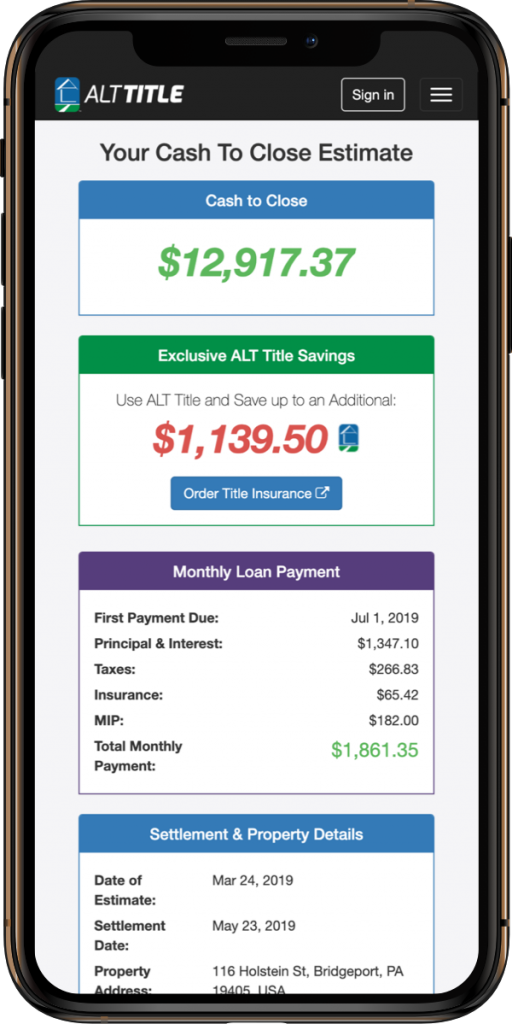
In the example below, we show you what a closing cost estimate looks like. And in under 5 minutes you can create your own estimates with just a few pieces of information on any property in PA, at my.cashtoclose.app. The tool is free to use and you can create as many estimates as you need on multiple properties without ever logging in. Or create a free account to save and return to your estimates later for editing.
(Click to enlarge or view this estimate online)

FAQs: Mortgage & Lenders
Mortgage Brokers don’t work for one specific lender; they survey the entire market to find you the best rate and terms available.
Using a mortgage broker gives you access to multiple lenders, from Rocket Mortgage and other national lenders to local banks. Ask them about a lender credit upfront then let them find you the best deal that fits your situation.
This is an easy one, yes. Unless you’re buying a house from a friend or relative, it’s highly unlikely that a seller would even consider your offer unless they’re relatively certain you can get a mortgage loan. Mortgage brokers, lenders, and credit unions all offer free pre-approvals.
1. Personalized Service
Local brokers often deliver highly personalized attention, taking the time to understand your unique financial goals. They’re typically more accessible for questions and guidance throughout the process, even during evenings and weekends, making the experience more convenient and responsive.
2. Knowledge of Local Market
Local brokers have in-depth insight into neighborhood real estate trends, property values, and even municipal requirements such as real estate and property transfer tax rates and schedules. This expertise helps ensure your financing aligns with local conditions and costs.
3. Advocacy
Established local brokers can add real value when it comes to getting your offer accepted. Their reputation and relationships within the community often carry weight. A personal call from your broker to the listing agent confirming your financial qualifications can help reassure the seller and make them more comfortable choosing your offer.
FAQs: Title Insurance & Settlement Services
The one-stop shop is the marketing illusion that you’ll get the best deal for multiple services all in one place. In fact, your agent and/or their broker will probably ask you to commit to using the in-house title company when you’re placing an offer on a house. It’s not necessary to commit at this time. Ask for a complete estimate with all related fees and tell them you plan on shopping around.
The reality is that although it sounds good, when you compare transparency, service and price, you’ll likely get better value from an independent title company like ALT.
No, it doesn’t. This is a false claim designed to fool consumers into believing it’s not worth shopping around for title insurance. While it’s true that state regulated title insurance premiums may not be discounted, many title companies charge non-mandatory miscellaneous title service fees which can add up to $700 or more to the total cost of your title insurance.
No, it won’t. Choosing your own title insurance company will not delay your closing. While some agents or lenders may suggest that sticking with their “preferred provider” is the only way to stay on schedule, that’s simply not true. This objection is often more about persuasion than practicality.
Agents and lenders who have financial ties to a title company may use the fear of delays to discourage buyers from shopping around. Since they can’t legally require you to use their affiliated provider, they rely on subtle pressure to steer you back toward their business interests.
Know Your Rights
Under federal law, you have the right to choose your own title company. At ALT Title, we work directly with your lender and agent to ensure your transaction stays on track. You’ll close on the same timeline, without the extra fees and with more savings.
Now that you know that title insurance related fees and services don’t cost the same everywhere and you can save money, you’ll want to start getting familiar with what the estimated cost will be once you know your price range and approximate amount of your future mortgage.
Those are the two numbers that you’ll need to determine the cost of the title insurance policy. Once you have that information, it’s time to start getting estimates for title insurance and settlement services.
You’ll want to order title search once your offer has been accepted. Once you place your title order and the home inspection is clear, a good title company will have the search completed in 5-7 business days.
If you’re being told you only have 6 days after your offer is accepted to order title insurance according to the terms of the PA Agreement of Sale, don’t sweat it. There’s a poorly written clause that was added to the agreement by the PA Association of Realtors in an attempt to give their brokers a greater ability to steer business to their in-house title company.
If you need a few extra days to decide, let your agent know as it’s not a big deal. Furthermore, the clause does not give your agent the authority to take control and order title insurance without your approval.
FAQs: Real Estate Broker/Agent
No, they don’t, but the smart ones will.
The idea behind the commission rebate is based upon an assumption that the seller is paying the commission to the buyer’s agent. Under that scenario, the buyer’s agent would rebate a portion of their commission to assist the buyer with their closing costs. Sort of like a thank you to the buyer for choosing them to be their agent. It’s also a smart business decision and will likely lead to future referrals.
If closing cost assistance or making sure you get the best deal on real estate services is your goal, you probably don’t want to hire the featured service providers on big home sites like Realtor.com or Zillow.
While these sites are great resources for finding a home, the agents and other service providers featured on their sites are often being charged up 40% of their commission as a referral fee in return for access to you as a client, so they’re often less flexible with offering commission rebates, waiving unnecessary fees, or offering the most competitive rates.
A buyer’s broker is a real estate agent who is hired by the buyer to represent their best interests throughout the home buying process. When the buyer and agent sign a formal agreement, the agent takes on a fiduciary duty, meaning they are legally and ethically obligated to act in the buyer’s best financial interest.
This includes:
– Putting the buyer’s needs ahead of their own
– Disclosing all important information that could impact the buyer’s decision
– Following all lawful instructions from the buyer
Having a buyer’s broker ensures you have a professional advocate on your side during negotiations, inspections, and every step of the transaction.
Commission rebates from your real estate agent or broker are considered as credits and need to be disclosed to your lender. With lender approval, the commission rebate can be applied as a credit against the amount of money you’ll need at settlement, which reduces your out of pocket expenses.
Or if the rebate puts you over the maximum credits allowed towards closing costs, your broker can write you a check once the transaction has closed.
No, they don’t.
The traditional percentage based commission model, which dates back to the early 1900s, is increasingly outdated and fading in relevance. Without getting lost in the industry politics that kept it alive for so long, here’s our recommendation:
Whether you’re buying or selling, you may find yourself responsible for paying some or all of your agent’s compensation. Negotiate in actual dollars, not percentages.
Why? Because percentages distort the conversation. An agent might claim that “1% is insulting,” but the tone changes when that same 1% on a $500,000 home simply becomes a $5,000 fee. When you focus on real dollars, the discussion becomes clearer, more equitable, and grounded in the actual value of the services provided.
Bottom line: Keep the negotiation in dollars. It leads to a more straightforward, good faith conversation that’s in line with the growing consumer push for clearer, more transparent compensation models.
FAQs: The Broker Admin Fee
What’s the deal with flat brokerage fees charged to the buyer?
Flat brokerage fees, sometimes called “administration” or “transaction” fees, are additional charges some agents or brokerages add on top of the regular real estate commission. These fees are typically meant to cover paperwork, processing, or internal administrative costs.
You may be told that this fee is not negotiable, but it often is. These fees are not required by law, and federal regulations do not require buyers to pay them as a condition of purchasing a home. Like many parts of a real estate transaction, they can be discussed and negotiated.
Bottom line: If you are able to eliminate this fee, you could save anywhere from $395 to $895, money that often comes in handy for moving costs, furnishings, or other post-closing expenses.
Yes. Unfortunately, consumers often times find themselves in the middle of compensation challenges between real estate brokers and their agents. As brokers search for ways to offset paying their agents a large majority of the total commission, some brokers pass additional fees onto the customer to increase revenue. This tug of war has nothing to do with the consumer and the law is on your side.
Consumers do not have to pay additional fees or use their real estate broker’s in-house service providers as a condition of buying real estate.
Know your rights. Under federal law, the buyer is not required to use any ancillary services provided by their real estate broker as a condition of purchasing real estate. That includes this admin fee. If you plan on shopping around, we suggest stating your intentions up front while interviewing potential agents. This prevents any hard feelings or misunderstandings once the emotions of house-hunting kick into high gear.
A reputable independent title insurance company will already be providing the majority of these services for no additional charge. It’s all included in the one-time title insurance premium that you pay at final settlement.
For instance, when you hire ALT to provide title insurance and settlement services, we manage your transaction and there’s no additional charge. And the total list of services that we perform on your behalf far exceeds the transaction management services offered by most real estate brokers.
See what’s included.
FAQs: Credits, Gifts, Grants
Another option to reducing the amount of personal cash you’ll need to buy a new home is receiving gift funds from a family member. Unlike seller credits, lender credits or commission rebates, there are no limits to the amount of gift funds that you can receive towards the purchase of your new home.
Gift funds can be used towards closing costs and your down payment, essentially making it possible for you to buy a new house without touching your savings.
Gift funds can also be applied to a buy down on your mortgage interest rate.
Pennsylvania and/or the local government where the property is located will sometimes offer first time homebuyers, or low-income buyers, grants that can be used for down payment assistance, but there are usually some strings attached.
Government grants typically require you to stay in the property for a specified period of time in order for the grant to be forgiven. If you decide to move before that window of time, or if you add or remove someone from the title to the property, you may need to pay all or a part of the grant money back. Most grants show up as a lien against the property which remains in place until the maturity date.
Here’s are some simple AI generated emails to guide you if you’re interested in a Seller Credit. You’ll want to keep your agent and your lender in the loop.
Let your agent know you’d like to request a seller credit. They’ll suggest an appropriate amount and include it in the offer.
Subject: Request to Include Seller Credit in Our Offer
Hi [Agent’s Name],
I’m ready to move forward with an offer on the property and I wanted to discuss including a seller credit to help cover some of my closing costs.
Can you advise on how much would be reasonable to request based on the price point and what’s typical in this market? Whether a percentage or flat amount, I’m open to your guidance.
Let me know how we would structure it in the offer, I’d like to run this past my lender first.
Thanks so much,
Make sure your lender is on board, as there are limits to how much seller credit you can receive.
Hi [Lender’s Name],
I’m preparing to make an offer on a home and planning to request a seller credit to help cover some of my closing costs, possibly around [x $ or %].
Can you let me know:
– The maximum seller credit allowed for my loan type?
– How it needs to be worded in the contract?
– If there’s anything I should be aware of from your end, like appraisal considerations or timing?
I want to make sure it’s structured properly so there are no issues later on.
Thanks in advance for your help!

ALT's Comprehensive Service for Private Transactions, For Sale by Owner
When the buyer chooses ALT for their title insurance, both Buyer and Seller can save money at settlement. View a list of our comprehensive services.
When a property catches your eye, estimate all your closing costs with this free tool.
It's 5-in-one mortgage calculator
- Calculate when payments will start and how much they'll be
- Calculate pro-rated closing costs, including insurances based on the settlement date
- Calculate state and local taxes including school taxes based on the exact address
- Calculate the funds you'll need for closing
- Identify areas where you could potentially further reduce or eliminate fees
More Helpful FAQs

Great service from Susan, Frank, and the entire team! I sold my Old City condo in a private sale. ALT Title handled the entire transaction, providing me with a purchase agreement, all necessary disclosure forms and handling the closing. I didn't have to use a realtor or attorney, which saved me thousands of dollars and lots of aggravation. I highly recommend ALT Title and would definitely use this business again in the future.
Jim Donovan on Google
Going with ALT was one of the best decisions I made as a first time home buyer.
The first title company I was connected to had a really nice digital interface & a snazzy app, but they also couldn’t/wouldn’t tell me what I should expect to pay on top of the cost of insurance. They were asking me to sign the insurance agreement and I still had no idea what other fees would be involved to close.
ALT was crystal clear: they gave me their estimate, and they charged me exactly that estimate, which plainly listed out what it did and did not include. The other title company insisted that the estimate was not realistic and too good to be true, but that’s what I paid. ALT covered/comped almost all the incidental costs over the insurance premium—no other title company’s price came close.
At that unbelievably low price, I also got super friendly, super responsive, knowledgeable service. Everyone at the company was great, helped make things happen fast, and also walked me through some of the non conventional aspects of our purchase. (Another thing the other title company not only could not do, but seemed unclear on themselves.)
Seriously: it seems like there should be a catch but there isn’t. Cannot recommend this company highly enough.
K.L., posted on Google
ALT saved me a few hundred dollars.
"I have been warned about ripoffs and hidden fees at settlement. They answered my many questions and helped to eliminate a phony charge the seller's realtor wanted to collect from me. They charged me exactly what PA dictates and NOTHING more--no conveyancing fees, no notary fees, no office use fees, no deed recording fees or any other invented fee of any kind."
Rich C., posted on Google
I was introduced to ALT through my realtor.
"The quote was unbeatable. No hidden fees at settlement. No surprises at all. They were on time and everything was smooth. Frank answered all the questions patiently and things to avoid after the settlement in regards to duplicate deeds in mail and other cautions. I would recommend ALT to anyone looking for a title company."
-Arvind J., posted on Google
Everyone was so great to work with at ALT.
"We used ALT recently to purchase a new home and they were fantastic. They made the process so easy and the best part was that you didn't have to fight with them over any hidden charges which sometimes happens with title companies. I recommend them highly."
-George H., posted on Google